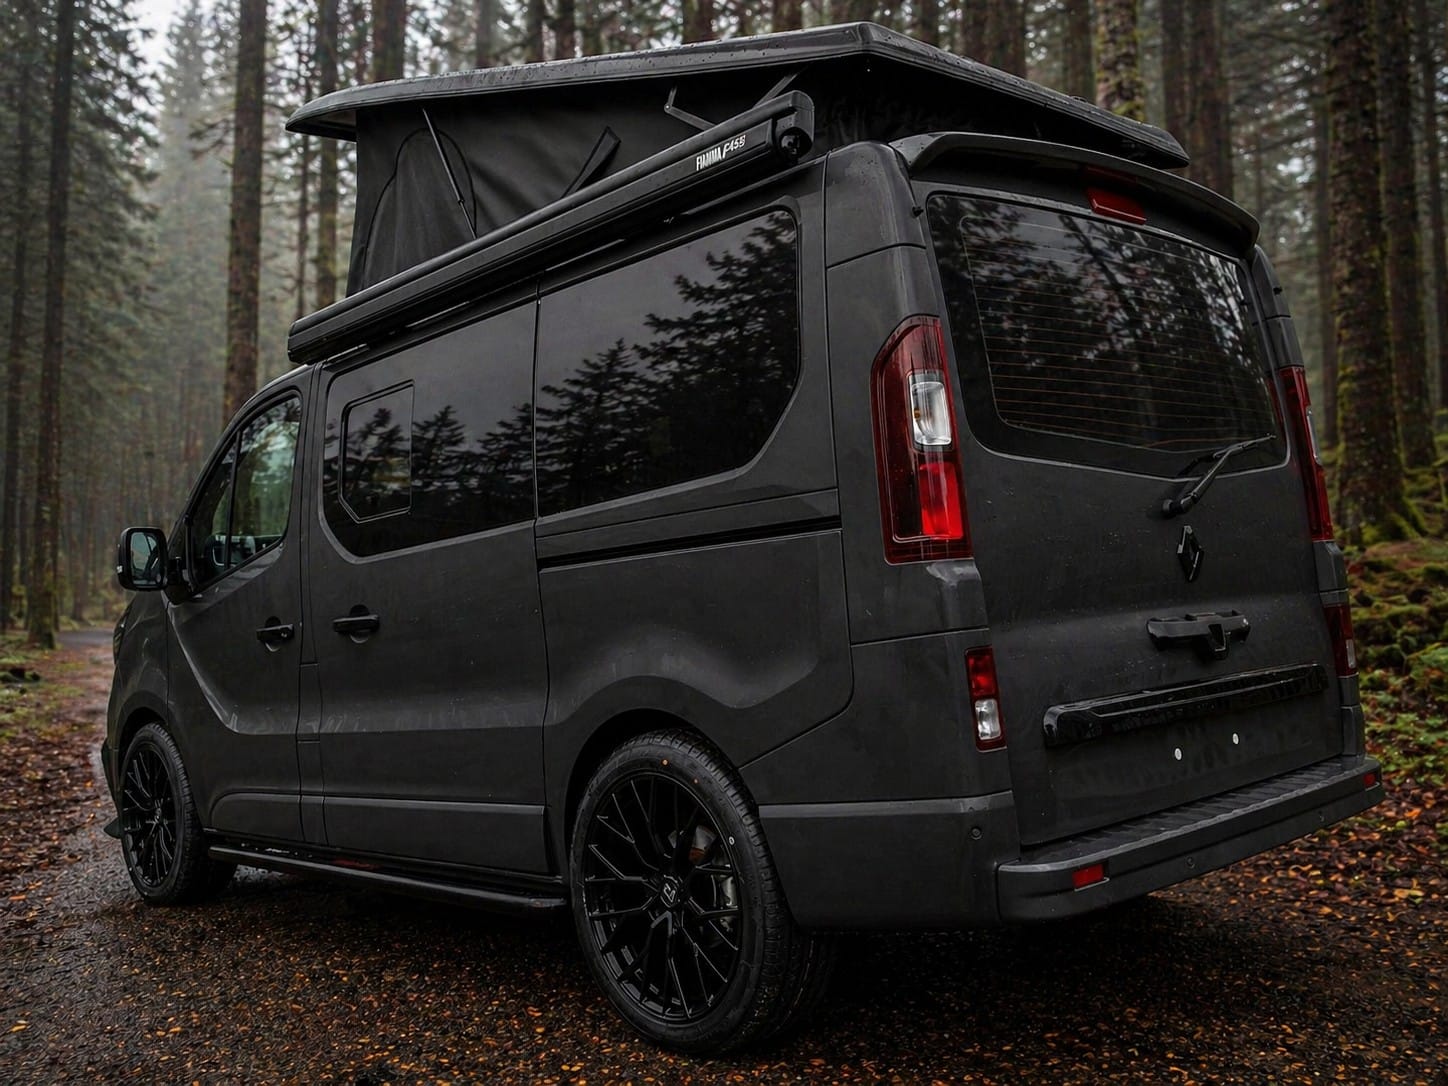
The most important thing about insuring a campervan is making sure the policy knows it is a campervan. A converted van is worth far more than the panel van it started as, and a standard van policy may only pay out the value of the van. For most owners of a professional conversion, the right answer is a specialist campervan policy on an agreed value.
This guide explains the choices in plain terms. We are a converter, not an insurer, so treat it as a starting point and check the details with the insurer before you buy.
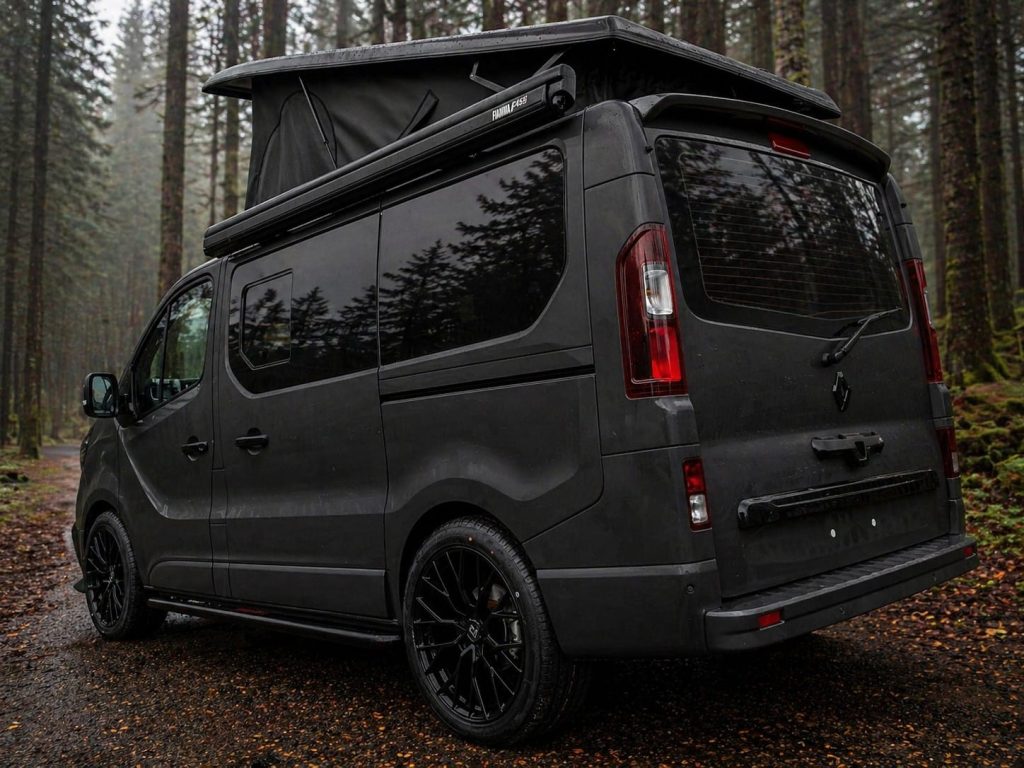
Agreed value or market value?
This choice decides what you get back if the van is stolen or written off.
A market value policy pays what a van like yours is worth on the day of the claim. An agreed value policy fixes the figure with the insurer in advance, so you both know what the payout will be.
Insurers ask for evidence before they agree a value. Just Kampers Insurance, for example, asks for seven photos and a request form, charges from £18, and the agreed value lasts a year. Without it, your cover is market value.
For a new or recent professional conversion, we would always ask for agreed value. The build invoice, the specification and good photos make the case for you.
Tell the insurer about the conversion
Insurers need to know about modifications. The Financial Ombudsman Service sets out how insurers can refuse claims or void policies when modifications were not declared. A bed, a kitchen, a pop top roof and a leisure battery are all modifications.
If you are buying a finished campervan, insure it as a campervan from the day you collect it. If you are converting your own van, speak to the insurer before work starts. Specialists set their own rules for vans part way through a conversion, so ask how long they will cover it in that state.
Does the logbook need to say motor caravan?
Not always. The DVLA can change a van’s body type to “motor caravan” if it meets its conversion criteria, but it says the body type does not affect the insurance category of the vehicle.
Insurers take different views. Some rate a campervan on how it is built and used, whatever the logbook says. Others, such as Comfort Insurance for self builds, want to see a motor caravan logbook or decide case by case. Howden says reclassifying can reduce premiums with some insurers. Ask your insurer directly before you apply to the DVLA.
Since 2019 the DVLA only changes the body type if the van looks like a motor caravan from the outside as well as inside. A pop top roof does not count as a high top roof in its checklist, so a pop top van may stay recorded as a van. Our campervan road tax guide explains the criteria and what the change means for your tax.
What to have ready when you get a quote
- The V5C logbook
- The build specification and invoice, showing what was fitted and by whom
- Recent photos inside and out
- Details of any tracker or security fitted
- Your warranty paperwork
Each of our listings sets out the full equipment list, and every van comes with a 3 year conversion warranty. Our builds are also compatible with Scorpion or Phantom tracker systems, which is worth mentioning to an insurer.
Driving in Europe
Every UK motor policy gives at least the legal minimum third party cover in the EU and a handful of other countries. According to gov.uk, you do not need a green card to drive in the EU (including Ireland), Andorra, Bosnia and Herzegovina, Iceland, Liechtenstein, Montenegro, Norway, Serbia or Switzerland.
Minimum cover is not the same as your full cover, though. Check with your insurer that theft, fire and damage cover also apply abroad, and for how many days. Some countries, including Albania, Moldova, Turkey and Ukraine, may still need a green card.
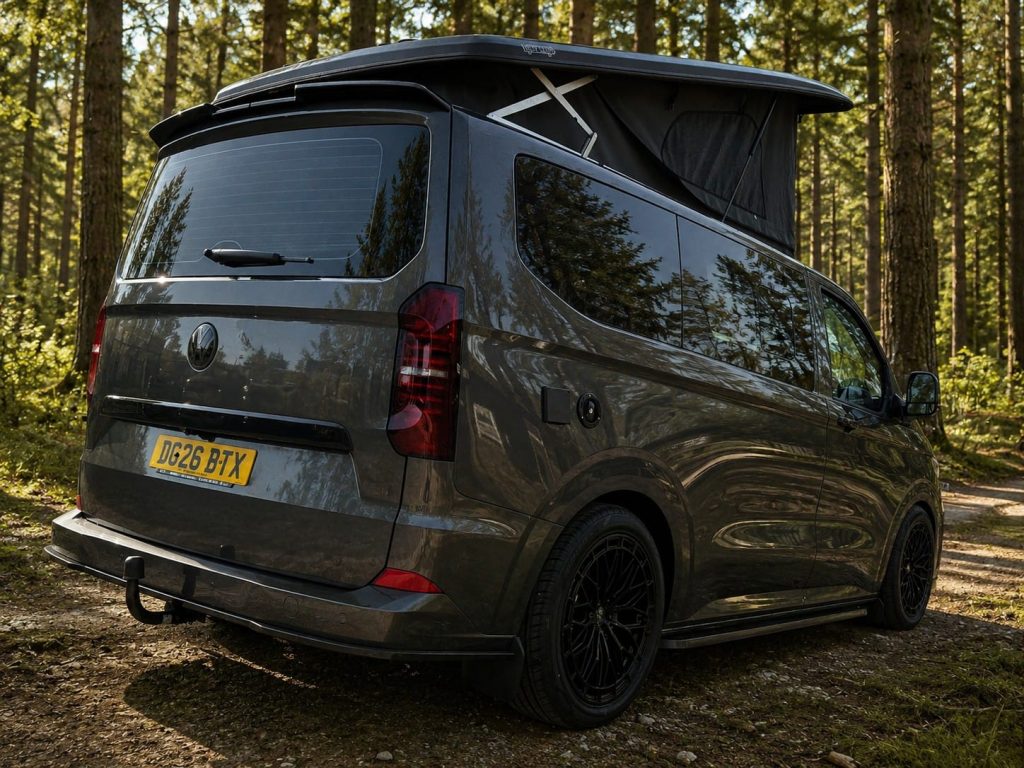
A few more things to check
- You need a category C1 licence for a motorhome over 3,500kg. Our vans are built on vans plated under that.
- Breakdown cover for a campervan should include recovery of the vehicle and its passengers, since you may be a long way from home with the family on board.
- Ask whether contents are covered, and up to what value. Bikes, cameras and camping kit add up quickly.
For more on costs, read our earlier guide how much does it cost to insure a campervan. And if you are still choosing a van, our buying checklist covers the rest.
Questions we get asked
Is campervan insurance cheaper than van insurance?
It can be, but it depends on the insurer, the van and you. Get a specialist campervan quote and a van quote for the same vehicle and compare what each one actually covers.
Do I need to reclassify my van as a motor caravan to insure it?
No. Some specialist insurers cover a professionally converted van as a campervan whatever the logbook says. Some ask for a motor caravan logbook, particularly for self builds, so ask first.
What is agreed value insurance?
A policy where you and the insurer agree the van’s value in advance, so you know what you will be paid if it is stolen or written off.
Do I need a green card to drive my campervan in Europe?
Not in the EU and several nearby countries. Check with your insurer that your full cover, not just the legal minimum, applies abroad.